Step 1
Reading your three reports
We sit with all three reports — Equifax, Experian, TransUnion — and go line by line until you know what is on them and why.
This does not change anything on your file. It is the reading, not the writing.
Brightness
Or skip all of that.
(216) 555-0148Monday to Thursday, 9 to 6. Friday until 3. You will get a person, not a queue, and nobody will ask for a card number.
Prefer to write? [email protected]
Cleveland, Ohio · English and Spanish
Second Wind is a small credit repair and coaching practice for people rebuilding after a bankruptcy, a hospital stay, a divorce or a layoff. We read your file with you, dispute what is genuinely wrong, and help you build the part that moves slowly and reliably. You pay nothing until the work is done.
If a late payment, a charge-off or a collection is genuinely yours and can be verified, no one can lawfully take it off your report. It falls off on its own, generally seven years after the first delinquency. Anyone promising otherwise is selling a fiction.
Not a number of points, not "in 90 days". It is unlawful for a credit repair organisation to promise a specific result, and the honest reason is simpler: nobody can see the inside of a scoring model or know what lands on your file next month.
Reports are free at annualcreditreport.com and disputes cost nothing to file. We wrote our whole method down and give it away. People pay us for time and a second pair of eyes, not for a secret.
What we do
There is no bronze, silver and gold here. There is one way of working, and the only question is how much of it you need.
Step 1
We sit with all three reports — Equifax, Experian, TransUnion — and go line by line until you know what is on them and why.
This does not change anything on your file. It is the reading, not the writing.
Step 2
Where something on a report is genuinely wrong, we help you dispute it under the Fair Credit Reporting Act and follow it through the 30-day investigation.
We do not dispute anything that is accurate. Accurate negative information cannot lawfully be removed.
Step 3
When a collector contacts you about a debt, the Fair Debt Collection Practices Act lets you ask them to prove it. We help you ask, properly and in time.
Validation is not a loophole. If the collector validates the debt, the debt is still yours.
Step 4
The part that actually moves a file over time: utilisation, on-time payments, a secured card or a credit-builder loan, and a budget you can survive.
We cannot promise a number or a date. Anyone who does is breaking the law.
What a dispute actually is
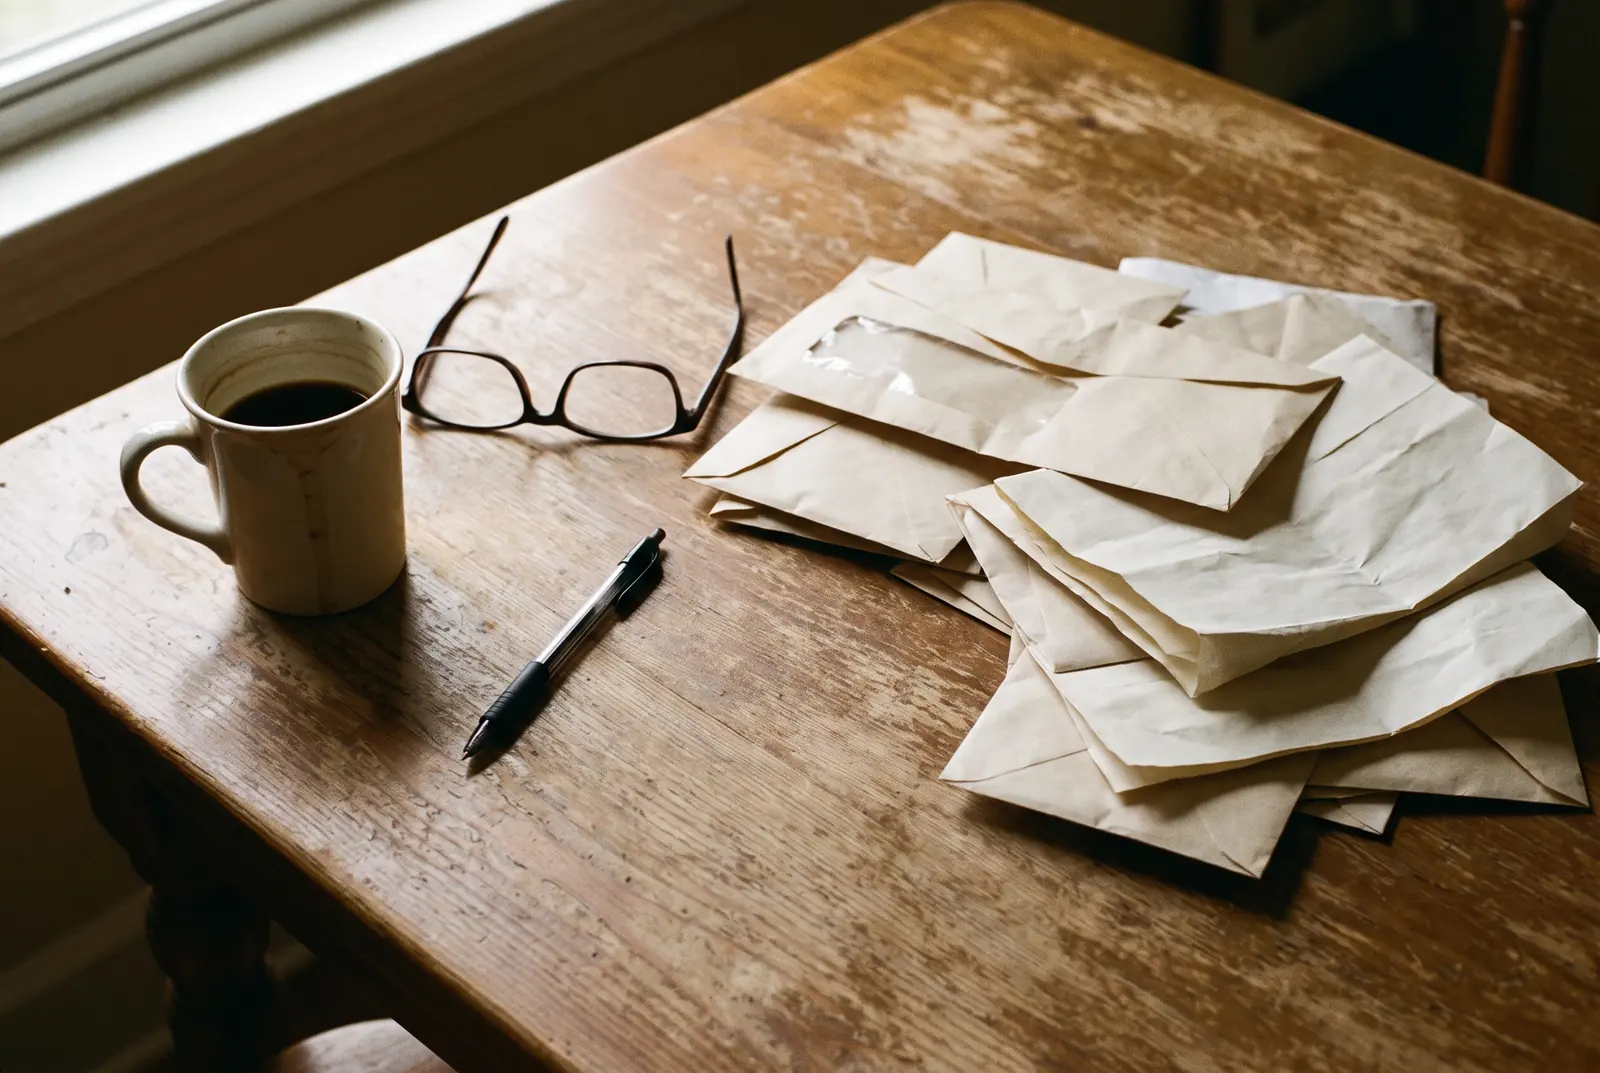
There is no portal, no algorithm and no lever anybody pulls behind the scenes. A dispute is a page you write, with the account, the reason it is wrong, and a marked copy of the report. It goes in an envelope. The bureau has about thirty days to investigate it and write back.
People expect something more technical, and are often relieved and slightly annoyed to find out that it isn’t. That is also why we can give the method away: there is no secret in the envelope. What we sell is the reading beforehand, the second pair of eyes on what is genuinely wrong, and someone who keeps the thirty-day clock for you.
A dispute is a letter. This one is illustrative — the real ones carry the account number, the reason, and a marked copy of the page. Postal addresses are left off on purpose: this is a demonstration site.
How it goes
Four stops, drawn the way the year actually runs: left to right, rising, with more distance between them than anybody wants. Each one says what happens and, underneath it, what does not — because for someone who has spent a year being chased, the second half is the half they lie awake about.
Half an hour, free, in person on Lorain Avenue or on the phone. You tell us what happened. We ask what you want to be able to do in two years — rent somewhere better, get a used car that starts, stop dreading the post. Nothing is signed and nothing is charged.
What doesn’t happen
Nobody asks for a card number, a Social Security number or a bank login. Nobody calls your employer, your family or your landlord. If you decide against us in the first five minutes, you can say so and we will still answer your questions.
Equifax, Experian and TransUnion do not hold the same information, and a mistake on one is often absent from the others. We pull all three, sit down with them, and go line by line until you can say out loud what each entry is, who owns it, and when it drops off.
What doesn’t happen
We do not open a new account, run a hard inquiry or apply for anything in your name. Reading your own report is a soft inquiry and does not affect your score in any way.
An account that is not yours. A balance that was paid. A date of first delinquency that has been re-aged. A collection that was already validated as someone else’s. Those get disputed under the Fair Credit Reporting Act, and the bureau has about 30 days to investigate and answer.
What doesn’t happen
We do not dispute accurate information, and we do not flood the bureaus with template letters hoping something slips through. That tactic gets disputes marked frivolous, and it can make an accurate file look worse rather than better.
Payment history and utilisation between them account for most of a FICO score. Getting a card under about 30 per cent of its limit, keeping every payment on time, and adding a secured card or a credit-builder loan if it fits your budget is slow, boring and the only thing that reliably works.
What doesn’t happen
We will not promise you a number, a date, or a jump of so many points, because no one lawfully can and no one honestly knows. We will not suggest debt settlement as a shortcut: it damages credit and it is a different thing entirely.
In their own words
We asked people what actually changed. Nobody said “my score”. They said they started answering the phone, or slept, or stopped feeling stupid.
To whoever reads these,
I put off opening the mail for about fourteen months. That is the honest version. After the surgery there were letters from the hospital, then letters from somebody who had bought the letters from the hospital, and I could not tell which was which.
What helped was somebody sitting down and separating them into two piles: the ones that were wrong, and the ones that were mine. The second pile was bigger. Nobody pretended otherwise.
I still owe what I owe. But I know what it is now, and I stopped screening my calls.
Hello,
The divorce closed two cards I did not know were still in my name. They went to collections before I found out. I assumed that meant I had done something wrong.
I had not, and it turned out one of the two was reporting a balance that was not mine. That one came off. The other one did not, because it was real, and they told me straight away it would not.
What I mostly got out of it was that I stopped feeling like a fool for not knowing.
Dear Second Wind,
After the layoff I paid the mortgage and let two cards go. I knew what I was doing. I would do it again.
When I came in I expected to be told off. Instead somebody drew me a picture of what those two accounts would do over the next six years and when they would stop mattering, and we made a plan I could actually stick to on what I earn now.
My daughter starts college in the fall and we are going to be alright.
These letters are illustrative composites written for a demonstration site, not real clients. They deliberately describe what changed in someone’s life rather than what happened to a number, because nobody — here or anywhere — can promise you a number. There are no star ratings on this site and no aggregate rating in its structured data, for the same reason.
After hardship
A credit report is not a character assessment, whatever it feels like at 2am. It is a list of what happened, in date order, with no column for why. The most useful thing we do is put the why back in — and then work out which entries are actually wrong.
Before you sign anything
A credit repair organisation may not charge or accept payment until the services it promised have been fully performed. Not a deposit, not a setup fee, not a “file activation” charge, not a first month in advance. If anyone asks, that is your answer.
It must say what will be done, how long it is expected to take, the total cost, and it must come with a separate written statement of your rights under state and federal law. You get a copy of everything you sign, and you get time to read it at home.
You may cancel without penalty or obligation at any time before midnight of the third business day after signing. The cancellation form comes attached to the contract; you post it or hand it back, and that is the end of it. Nobody will call to talk you out of it.
Questions people actually ask
No. If the information is accurate and the furnisher can verify it, nobody can lawfully have it removed, and anyone who says otherwise is either selling you something or breaking the law.
What we can do is make sure it is being reported correctly — the right balance, the right status, the right date of first delinquency, and not duplicated across two collection agencies — and then help you plan around the date it falls off, which for most negative items is seven years from that first delinquency.
We will not answer that, and you should be wary of anyone who does. Under the Credit Repair Organizations Act it is unlawful for us to promise a specific result, and even setting the law aside, nobody can see inside a scoring model or know what else will land on your file next month.
What we can tell you honestly is which factors are weighing on your file right now, roughly how much each of them is generally worth, and what the realistic ceiling looks like once the accurate items age.
No. Not a deposit, not a setup fee, not a first month in advance. A credit repair organisation may not charge or accept payment until the services promised have been fully performed, and we do not ask for one under any name.
You also get a written contract before any work begins, and three business days to cancel it without penalty or reason.
No, and the difference matters. Debt settlement means stopping payment and negotiating to pay less than you owe; it usually damages your credit badly and can leave you with a taxable forgiven balance. Consolidation moves debt into one loan.
Credit repair is narrower and duller than either: it is about making sure what is reported about you is accurate, and then rebuilding. We are not a settlement company and we do not take a percentage of anything.
Yes, though not the point people expect. A discharged Chapter 7 stays on your report for ten years from filing and cannot be removed while it is accurate. But the individual accounts included in it should be reporting a zero balance and a status of "discharged in bankruptcy", and very often two or three of them are not.
Beyond that, the rebuilding is unusually effective after a discharge, because your debt-to-income has changed and you cannot file again for years — which is exactly why secured card issuers are willing to talk to you. See after hardship.
The first conversation is free, it takes about half an hour, and it ends with you knowing what is actually on your file and what can honestly be done about it. If the answer is "nothing we can charge for", we will tell you that, and you will still get the plan.
Not ready to talk to anyone? Take the guide and do it yourself. It is the same method, it costs nothing, and you never have to tell us you used it.
Demo control
A scheme lends its hue and its intensity. It never lends its lightness, so the deep sections stay deep, the paper stays paper, and every one of these clears its contrast floor in both daylight and dark before it is offered.
This dial cannot move the disclosures. The required notices, the three-day right to cancel, the do-it-yourself notice and the two colours that mean can andcannot are not in the table it writes to. They carry meaning rather than branding.
Applies immediately
Set it how you read
Scales the type only. The layout does not grow with it.
Black on white, or white on black, with hard rules.
Stops the drifting motes, the parallax and every scroll-driven animation.
Underline every link in the page body, not only on hover.
These are real controls, not a badge. This demo has not been through a formal WCAG audit, so it does not claim one.
What this site keeps
There is no analytics on this site, no advertising pixel and no third-party script, so there is nothing here to track you with. The only thing it would like to remember is how you set it: light or dark, which colour scheme, and your reading-comfort choices — text size, contrast, motion and link underlines.
Until you answer, those live in this tab only and disappear when you close it. Say yes and they are kept on this device instead. Say no and nothing durable is written — except your answer, so we do not ask again.
Either button closes this. You can change your mind from Storage choices at the foot of any page.